DIGITAL MARKETING: The OPTIMUM v2.2 Advantage

OPTIMUM v2.2 Ecosystem is not a checklist, it’s a continuously evolving system designed to turn insight into impact. Built around a closed-loop methodology, it moves seamlessly from observation to execution and refinement, ensuring every decision is grounded in real data and every action drives measurable progress.

By connecting strategy, content, and performance into a single unified process, OPTIMUM eliminates guesswork, exposes hidden opportunities, and compounds results over time – so nothing is created without purpose, and nothing is left to stagnate. Backed by four decades of marketing, digital marketing, and business consultancy experience, this is a model built on what actually works; refined, tested, and proven in the field.

If you’re ready to replace fragmented tactics with a system that delivers consistent, scalable growth, it’s time to put OPTIMUM to work. Contact me today for more information.


OPTIMUM v2.2

O — Observe
The system ingests and interprets data across content, search environments, and user behaviour. This is not passive reporting; it’s active pattern recognition, identifying intent signals, gaps, and opportunities others miss.

P — Profile
OPTIMUM builds a precise picture of the current state: brand positioning, content quality, search visibility, and conversion pathways. It defines where you actually stand, not where you think you are.

T — Target
It isolates the highest-leverage opportunities- keywords, topics, audiences, and structural fixes that will drive disproportionate impact. Focus is everything here.

I — Ideate
Using its prompt architecture, OPTIMUM generates strategic directions, content angles, and optimisation pathways aligned to both SEO and GEO environments.

M — Make
Execution happens here. High-quality, intent-matched outputs are produced – content, structures, and assets designed to perform across search engines and generative engines alike.

U — Upgrade
Existing assets are refined and enhanced. OPTIMUM doesn’t just create new, it systematically improves what already exists to unlock hidden value.

M — Measure
Performance is tracked, interpreted, and fed back into the system. Not vanity metrics, but meaningful indicators tied to visibility, engagement, and conversion.


In Plain Terms

OPTIMUM is a closed-loop system:

Observe → Profile → Target → Ideate → Make → Upgrade → Measure → (repeat)

Each stage feeds the next. Nothing is isolated. Nothing is wasted.


Why This Matters

Most businesses:

  • Create without insight
  • Optimise without direction
  • Measure without action

OPTIMUM eliminates that fragmentation.

Every output is:

  • Informed by real data
  • Aligned to strategic goals
  • Built to improve over time

DIGITAL MARKETING: Legacy Business and Mistaken Identity.

This week by utilising my analysis tool, OPTIMUM v2.2, in my role as a business consultant I can share three real-world cases where the digital tool revealed what conventional Search Engine Optimisation (SEO) audits simply miss – from a digital disruptor poised to overtake an established rival, to a business losing ground in AI Summaries because of another company’s bad reviews. If you think your Google SERPS and review ratings tell the full story, read on.

Was it Sir Richard Branson who said, “Train good managers well and pay them enough so they won’t want to leave“? Sound advice, as it turns out.

When senior managers and directors walk out of a legacy business that has only dipped its toes into the digital world, then immediately set up a rival operation that is leaner, more digitally confident, and energised by the founders’ drive, they do not simply become competitors. They become disruptors, and potentially an existential threat.

This week I ran OPTIMUM v2.2 across two businesses in entirely different sectors. In both cases, the data points in the same direction: the newcomer is on course to overwhelm the incumbent within six to twelve months in all areas of the business.

One of the new entrants scores particularly well across digital marketing, SEO and Generative Engine Optimisation (GEO) which in layman’s terms means AI Summary inclusion. The only reason it sits behind the legacy player in any notional local league table is that its five-star reviews are too recent to have yet shifted the algorithm’s overall rating. That will change in a few months to compound their initial success.

Another case threw up something altogether more abstract. A well-regarded Midlands business, with years of strong Google reviews and solid standing across industry portals, returned an unexpectedly low trust score. The reason? Another firm operating in the same region has a remarkably similar name and a TrustPilot rating of just 1.2 out of 5. The AI systems are conflating the two, and my client is being dragged down by a reputational deficit that has nothing to do with him.

The fix is straightforward in principle: create a TrustPilot profile using the exact business name, address and contact details, build up a body of genuine five-star reviews, and re-run the assessment in a few months. It is a concrete, actionable win that would not have surfaced without running the OPTIMUM Ecosystem tool.

On a broader point: when I run typical local searches, the first few pages of results are dominated by larger players with serious SEO investment or the budget to buy their way to the top. That is not a battle most SMEs can realistically win on Google.

AI Summaries are a different matter. At present, the only route to inclusion in those summaries is through genuine GEO optimisation of your website. There is no shortcut and no media buy. My view is that, right now, every town and city represents an open opportunity for a switched-on business to own the AI Summary space for its sector or niche. Not only can that battle be won, but the businesses that establish authority early will carry that advantage forward. The AI systems will keep referencing those early signals as they generate future responses, and that compounding effect is only going to grow.

That combination of proprietary diagnostic data and hard-won experience is precisely what makes the difference between an interesting report and a result. The tool sees what the algorithms see; the consultancy knows what to do next. If you would like to find out what OPTIMUM v2.2 reveals about your business, your competitors, or your AI Summary visibility, I would be happy to talk.

ESTATE AGENCY: Wake Up, You Have Website Paralysis

There is a clear and consistent issue across local estate agent websites. They are not built to generate business. They are built to exist.

Most agents rely heavily on portals like Rightmove and Zoopla for leads, treating their own website as a secondary asset. That creates a risk. If portal costs rise or performance drops, many firms have no reliable, owned source of enquiries. The automotive sector has already felt this pressure with Autotrader. Estate agency is heading in the same direction.

At the same time, most websites are under-optimised.

Common problems include thin location pages, duplicated property content, weak internal linking and outdated metadata. More importantly, there is little alignment with how people actually search. Buyers and sellers are asking detailed, intent-driven questions, yet very few agent websites provide meaningful answers.

This is where the real gap sits.

Content is often shallow and self-focused rather than useful. There is little coverage of the full customer journey, from early research through to decision. As a result, agents miss out on valuable organic traffic and fail to build authority in their local market.

Generative search adds another layer. Most sites are not structured in a way that AI systems can easily understand or trust. Without depth, clarity and consistency, they are unlikely to appear in AI-driven results.

Keyword gap analysis typically reveals hundreds of missed opportunities across local, long-tail and high-intent searches. Opportunity gap analysis then shows which of these are actually worth pursuing based on competition and conversion potential.

The bigger issue is strategic. Most estate agent websites are not designed as end to end marketing systems. They attract limited traffic, offer little engagement and convert poorly.

A more effective approach combines technical SEO, structured content, GEO readiness and clear conversion pathways. This turns a website from a passive brochure into an active source of instructions.

The opportunity is significant. Agents who invest in their own digital presence can reduce reliance on portals, improve margins and build a more stable pipeline of leads.

Right now, most are not doing this.

That is where the advantage lies.

To establish where you are today and understand where you could be tomorrow contact me and we can run an OPTIMUM V2 Ecosystem report.

DIGITAL MARKETING: Introducing OPTIMUM V1 – How Will You Score?

OPTIMUM V1 Ecosystem – a comprehensive SEO and Generative Engine Optimisation audit delivering actionable insights, competitor gap analysis, and AI citation readiness, built on ethical, GDPR-compliant foundations.

State Of The Art, Ethical and Regulatory Compliant.

Like to learn more?

The OPTIMUM V1 Ecosystem is a fully integrated SEO and Generative Engine Optimisation (GEO) audit framework built for organisations that expect more than surface-level diagnostics. Designed for digital leaders, marketing directors, and growth-focused teams, it delivers a forensic, end-to-end assessment of search visibility, content performance, and AI discoverability – all within a single, coherent system.

At its core, OPTIMUM V1 goes beyond conventional auditing. It identifies structural weaknesses, uncovers competitive gaps, and produces clear, prioritised recommendations grounded in real-world impact. From technical SEO and content architecture through to entity optimisation and AI citation readiness, every output is engineered to be actionable, not theoretical.

What sets the ecosystem apart is its breadth without compromise. Each module – including advanced competitor gap analysis and GEO alignment – operates to a consistent standard of depth and accuracy, ensuring no blind spots across the modern search landscape. The result is a holistic view that connects traditional ranking factors with emerging AI-driven discovery patterns.

Equally critical is its foundation in ethical practice and regulatory compliance. OPTIMUM V1 is built with strict adherence to GDPR principles, including data minimisation and zero retention of personal data. Its crawler operates transparently, respecting robots.txt protocols, enforcing rate limits, and defaulting to non-intrusive analysis where permissions are restricted. This is not just best practice – it is non-negotiable design.

For businesses navigating an increasingly complex search environment, OPTIMUM V1 provides clarity, precision, and strategic direction — a high-calibre audit ecosystem designed not only to diagnose performance, but to define the path to sustained visibility, authority and profit.

For more information please contact me. 

AUTOMOTIVE: From Renting To Owning

There’s a shift happening in the U.K. motor trade right now, and it’s a bit more serious than the usual platform grumbling.

Dealers aren’t just questioning spend with Auto Trader Group anymore. Some are actively cancelling. The reasons are stacking up in the same direction:

  • Rising costs
  • Increasingly complex packages
  • ROI that no longer justifies the outlay

On its own, that would be a familiar cycle. Platforms get expensive, dealers push back, things rebalance.

But this time there’s a second force hitting at the same time.

Search itself has changed.

Platforms like Google are now answering queries directly through AI summaries. Buyers are getting what they need without clicking through to marketplaces or dealer sites at all. In a previous article I explained ‘Zero Click and Position Zero’. Early research, comparisons, even shortlists are being shaped before anyone enters the traditional Internet funnel.

So dealers are facing a double hit:

Paying more for marketplace exposure

While a chunk of demand never reaches marketplaces in the first place

That’s not a pricing problem. That’s a structural one.

The instinctive move is to look sideways. Reach out to other dealers. Test CarGurus or Motors see if the numbers improve. Some do, briefly. But most feedback lands in the same place. Variable lead quality, unclear attribution, no consistent step change in performance.

Because the underlying issue hasn’t been addressed.

Demand is shifting upstream.

More buyers are starting and finishing their research in environments where the answer is presented instantly. No click required. No listing viewed. No enquiry made until much later in the journey.

Which raises a simple question.

If fewer people are clicking… what exactly are you paying for?

There is another way to look at it.

Instead of continuing to rent demand through third-party platforms – e.g. the increasingly expensive Autotrader, dealers can start to build visibility in the places where decisions are now being shaped. Not by chasing rankings in the old sense, but by creating content that answers the exact questions buyers are asking in a format AI can use.

For example:

  • “Do EV batteries fail outside of warranty”
  • “Best used SUVs under £20k”
  • “Are BMW diesel engines reliable”

Right now, most dealer websites don’t compete on any of this. They’re built to display stock, with a narrative made up of specification, not to demonstrate understanding.

That’s the gap.

And increasingly, it’s where influence sits.

Because the real prize now is not just appearing on page one. It’s being included in the answer itself. The source behind the AI summary – AKA AI Summary Citation or Position Zero.

The voice that shapes the shortlist before a buyer ever clicks.

Early signs suggest that reallocating even a portion of marketplace spend into this kind of approach, content built for answers, structured properly, technically clean, can start to build visibility that compounds over time.

Not instant. But owned.

Strategic Honesty in the Age of AI: Why Your Online Story No Longer Adds Up

In a world where jobs and contracts are becoming more scarce AI scans every CV and social feed, smoke and mirrors no longer cut it. Strategic Honesty, aligning what you say with what can be seen and measured – is the only way to be credible, legible, and truly noticed.


We have spent the last decade curating ourselves like celebrities and our possessions like artefacts. Clean lines, flattering filters, the right captions and hashtags. Announcements we think peaople want to know all about “Delighted to announce” without the quieter truth that three months earlier it nearly all went South. It was never quite deception, more a kind of collective agreement to present the highlight reel and leave the rest quietly sidelined.

Now the machines are here, and they do not care about your lighting.

An Applicant Tracking System (ATS) which utilises AI does not admire your resilience or your judgement. It does not recognise that you were the person everyone relied on when things went wrong, or that you held a business together through sheer force of experience. It looks for patterns, matches terms, and scores you in silence. Increasingly, it cross-checks what you say against what it can find elsewhere, not just your CV but the broader long-tail of information you have left behind. Being capable, productive and quietly effective is no longer enough if those qualities do not translate into something the system can actually detect.

What used to be a loosely held narrative is now something closer to a personal dataset, and that shift is where things begin to fracture.

You can see it at both ends of the spectrum. The fifty-five, sixty, sixty-five year olds sending out applications into the void, with decades of experience compressed into keywords that unknowingly won’t land. Careers built on judgement, relationships and instinct, none of which scan particularly well. Their social presence, if it exists at all, is often skeletal, sometimes frozen in 2019. Honest, perhaps, but not legible to the systems now doing the filtering, and therefore not visible at all.

At the other end are the thirty-somethings with immaculate feeds and a constant stream of apparent momentum. Their career (or entire business) looks like it is flying, all new wins and forward motion. It holds together until you look more closely. Six orders in nine months dressed up as scale. Activity mistaken for traction. The story feels convincing at a glance, but the underlying signal is thin, and that thinness is exactly what machines are designed to detect.

The hesitation here is understandable. If perception drives opportunity, why risk puncturing it? Why swap a polished narrative for something that might look smaller, earlier, less certain? There is a real fear of losing face, of no longer looking like a good bet. But there is a counterintuitive effect at play. In a landscape full of inflated signals, a precise account of what is actually happening can attract a different, often better aligned kind of attention. Not sympathy, but relevance. The right people are not looking for theatre. They are looking for something they can understand and trust. That word authenticity reappears.

These are very different situations, but they share the same underlying problem. The story being told and the signal being emitted are out of sync. For years, a degree of polish smoothed over that gap. You could rely on an experienced and appreciative human reader to fill in the blanks, to give you the benefit of the doubt, to sense potential where the evidence was incomplete. That audience is no longer guaranteed.

What is needed now is what you might call Strategic Honesty. Not radical transparency and not personal branding as theatre, but something more deliberate. A way of presenting yourself that aligns what you say with what can be seen, measured and verified.

In this environment, inconsistency carries a cost. If your profile says one thing, your history suggests another and your output tells a third story, you do not come across as intriguing. You come across as incoherent. Incoherence is something machines are very good at spotting and increasingly something humans have less patience for as well.

There is also a quiet fatigue setting in. Spend any time scrolling and everyone appears to be winning. Every move is a step up, every project a success, every announcement another rung climbed. It stops being inspiring and starts to feel synthetic, a kind of ‘achievement theatre’ that no longer convinces in the way it once did.

The people who cut through that will not be the ones who simply invert the performance and start broadcasting their worst moments. That is not honesty so much as a different flavour of the same performative instinct. What stands out instead is clarity. People who are easier to read because the story, the evidence and the output all point in the same direction.

For the experienced candidate, that means translating a long career into clear and current signals, showing where their knowledge sits now rather than where it was first earned. It means making visible the value that was previously assumed, so that systems which cannot infer it can still recognise it. For the younger operator, it means bringing continuity to the narrative, explaining the numbers plainly and showing what is real rather than what merely looks good at a glance. Six solid pieces of work, clearly articulated, will often travel further than a vague sense of constant motion. In both cases, the aim is not perfection but believability.

Strategic Honesty, in that sense, is about a triumvirate of alignment. Your public story, your actual capability and your visible output should broadly reinforce each other. Not flawlessly, but convincingly enough that both machines and humans can follow the thread without friction.

In a system that increasingly measures everything, credibility becomes harder to fake and easier to verify. That, in turn, makes it more valuable than the polished illusion it replaces.

So the answer is not to tear down the façade completely and invite the world in. That misses the point. The shift is quieter and more practical than that. Strip out the inflation, lose the vague bravado and replace it with specifics. Show the work as well as the result. Admit the gap where it matters and demonstrate how you are closing it.

The story that sticks isn’t the flashiest. It’s the one that’s honest enough to be believable, and authentic enough to recognise.

Finally, if all fails, an old strategy; print out your CV, write a cover letter, visit the business, ask for the manager and personally hand over your details with a smile. That got many people a job when I was the other side of the desk.

AUTOMOTIVE: Porsche Profits Apply The Big Stoppers

Porsche, once the golden child of German engineering and luxury performance, has hit an unexpected crisis in 2025. After years of record profits and unmatched prestige, the carmaker has reported a devastating fall in earnings, with operating profit plunging by more than 99 percent. The decline raises urgent questions about Porsche’s electric strategy, global sales slump, and future in an increasingly uncertain automotive market.

There was a time when the air in Zuffenhausen smelled of success and the confidence of endless growth. Porsche was the brand that never stumbled, the company that made perfection seem routine. Yet this year the balance sheets told a very different story.

For the first time in living memory, Porsche has posted a loss. Not a minor dip or a brief misfire, but a full-blown financial skid. In the third quarter of 2025, the company recorded an operational loss of nearly one billion euros. Across the first nine months of the year, profits collapsed from around four billion to just forty million. The figures landed like a crash through the guardrail at La Source.

The roots of Porsche’s decline lie in its costly electric gamble. Determined to lead the luxury EV revolution, the company poured billions into its own battery programme and an ambitious range of electric cars. The goal was clear: by 2030, eighty percent of new Porsches would run silently rather than roar. The market, however, had other ideas.

Buyers loved the Taycan’s design and speed, but hesitated at the price and limited range. High costs and lukewarm demand forced Porsche to retreat. The battery division was scrapped, new electric SUVs cancelled, and the firm took a three billion euro write-down. The pivot back to hybrids and combustion engines restored a little sanity, but the damage was done. Investors saw indecision. Customers saw confusion.

External pressures made things worse. In America, new tariffs on European luxury cars have already cost Porsche hundreds of millions of euros. Prices have risen, and demand has fallen. Across the Pacific, China’s once-booming market for Western prestige cars has cooled sharply. Sales dropped by more than twenty-five percent as domestic electric brands took centre stage.

Europe offered no comfort either. Economic fatigue and tighter emissions laws have hit the high-end market. Even the 911, the timeless heartbeat of Porsche, faces an uncertain future in a world determined to phase out petrol. Volkswagen Group, Porsche’s parent company, has reported its own steep drop in profit, much of it linked to this turmoil in Zuffenhausen.

The response has been fast and severe. Around four thousand jobs have already gone, and restructuring costs have topped three billion euros. Meetings that once celebrated lap times now focus on cost savings. Michael Leiters, Porsche’s new chief executive and a former McLaren man, has inherited the unenviable task of restoring confidence while steering a bruised and bewildered company back to growth.

Behind the scenes, engineers are refocusing. Porsche will rely on its most loyal strengths: craftsmanship, performance, and the feel of quality that no algorithm can reproduce. Future cars will blend petrol and electric power rather than replace one with the other. The idea is to rebuild gradually, balancing innovation with identity.

For decades, Porsche was defined by certainty. Every car, from the 911 Turbo to the Macan, carried the same message of precision and purpose. But the modern world is no longer so simple. Customers expect luxury, performance and sustainability in a single package. Governments demand cleaner cars. Markets demand profit. Somewhere in that storm, Porsche lost its footing.

Yet history suggests the brand knows how to recover. In the early Eighties, Porsche faced a similar reckoning. Sales were weak, costs were high, and purists feared the end of the 911. The company survived by listening to its engineers rather than its accountants. It rediscovered its essence. That may be the lesson Zuffenhausen needs again today.

If Porsche can blend its heritage with a clearer, more measured path to electrification, it could regain its balance. The 911 remains a global icon, and the Taycan, for all its struggles, proved that electric Porsches can still thrill. What the brand needs now is consistency and patience. The next great Porsche story will not be written in spreadsheets but in steering feel, design integrity and engineering bravery.

For now, though, Porsche’s halo has dimmed. The numbers are harsh, the markets unforgiving, and the pressure immense. Yet if any marque can turn a loss into a lesson, it is the one that made imperfection an art form.

What Porsche Could Do Next?

– Refocus the product line: Build hybrids and performance models that maintain the emotional core of the brand while easing customers toward electric power.
– Control production costs: Simplify supply chains, delay unnecessary launches, and invest only in platforms that deliver profit and flexibility.
– Strengthen brand storytelling: Reignite the emotional link between car and driver through heritage design cues and motorsport engagement.
– Win back key markets: Adjust pricing and marketing strategies in the United States and China to match shifting buyer sentiment.
– Prepare for the long term: Develop a steady, sustainable EV roadmap that doesn’t gamble the company’s identity on unproven demand.

If Porsche manages to balance its heart with its head, it will emerge stronger. The figures may be grim today, but the brand’s legacy of resilience remains intact. The brand is used to the smell of victory.

DIGITAL MARKETING: AFFORDABLE AI & SEO HEALTH CHECK

Is your business visible when it matters most?

With Google’s AI summaries now dominating search results, the digital landscape has shifted dramatically – and quickly.

What worked last March might be costing you customers today.

As an SME owner or director, you’re juggling countless priorities. But here’s the reality: whilst you’ve been focused on running your business, the way customers discover and evaluate companies has fundamentally changed. Google’s AI now determines which businesses get featured in those crucial summary boxes that appear before traditional search results.

The question isn’t whether you need a digital presence – it’s whether your current one is working.

Many SME owners assume their website and social media are “sorted” because they exist. But an empirical analysis often reveals:

• Your ideal customers can’t find you when they’re actively searching

• Competitors with weaker offerings are appearing ahead of you

• Your digital messaging doesn’t reflect your actual business strengths

• You’re missing opportunities in channels where your customers actually spend time

This isn’t about expensive overhauls or complex tech solutions. It’s about getting an objective, data-driven assessment of where you stand and what simple changes could make the biggest impact.

The businesses thriving right now aren’t necessarily the biggest – they’re the ones that understand their digital footprint and have aligned it with how customers actually behave online.

If you’ve been putting off that digital review because it feels overwhelming or expensive, consider this: the cost of not knowing where you stand is likely far higher than finding out.

The bonus is that my service is not only invaluable, but very affordable – I’ve started and run SME sized businesses so I understand cost control and value.

Don’t let your competitors steal tomorrow’s customers whilst you’re serving today’s.

Message me to get the ball rolling. 

AUTOMOTIVE: Tesla In Reverse

Tesla faces its gravest crisis yet with plummeting sales, legal battles, and brand toxicity. Can Musk’s desperate sales intervention save the company he built?
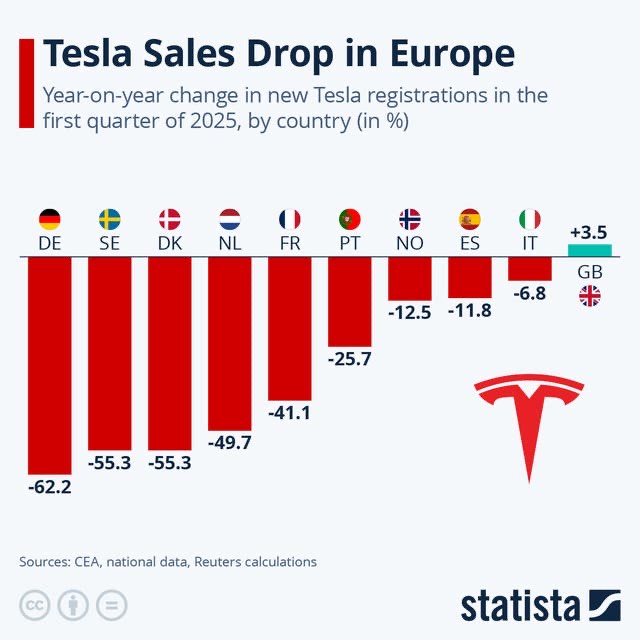
Tesla Sales Slump. A Company In Reverse.
The numbers tell a brutal story. Tesla’s second-quarter deliveries plummeted 13.5% year-on-year to just 384,000 vehicles, whilst European sales collapsed by as much as 45% in early 2025. Even in Tesla’s stronghold markets of China and the United States, rivals including BYD, Volkswagen, and Hyundai are systematically dismantling the company’s once-impregnable market position.

What began as isolated competitive pressure has metastasised into an existential crisis encompassing product stagnation, mounting legal challenges, and a brand toxicity that would have been unthinkable just two years ago. Elon Musk’s response – personally commandeering Tesla’s sales operations from the company’s headquarters – represents either inspired leadership or desperate theatre. The evidence suggests the latter.

Tesla’s troubles extend far beyond routine quarterly fluctuations. Industry analysts point to a fundamental product problem: the company has launched no genuinely new mainstream models since the divisive Cybertruck, leaving its core range looking increasingly antiquated. The Model S and Model X, now approaching their second decade, lack the technological edge that once justified premium pricing, whilst even the refreshed Model 3 and Model Y variants have failed to generate meaningful market excitement.

Manufacturing bottlenecks from Model Y production transitions have exacerbated inventory buildups, creating the paradox of falling sales alongside unsold stock. “Tesla is caught between worlds,” explains one former executive who departed the company last year. “They’re trying to maintain premium positioning whilst competing on volume, and it’s not working.”

The human cost of these missteps extends beyond shareholders. Recent months have witnessed an exodus of senior talent, including the head of North American sales and key battery engineering leaders, suggesting internal recognition that current strategies are failing.

Perhaps more damaging than operational setbacks is Tesla’s reputational crisis. Musk’s increasingly vocal political alignment, particularly his association with Donald Trump, has triggered what industry observers term a “consumer revolt” in traditionally progressive markets where Tesla once dominated.

The “Tesla Takedown” movement, documented across social media platforms, encompasses everything from organised boycotts to physical vandalism of vehicles. Resale values have declined accordingly, with specialist automotive data firms recording measurable drops in Tesla’s brand perception scores throughout 2025.

“We’re seeing something unprecedented,” notes Professor Sarah Davidson, who studies automotive consumer behaviour at Warwick Business School. “Political polarisation is directly impacting purchase decisions in ways we’ve never measured before. Tesla owners are reporting embarrassment about their vehicles.”

Tesla’s troubles extend into America’s courtrooms, where multiple high-stakes cases threaten both immediate operations and long-term viability. California’s Department of Motor Vehicles is pursuing a 30-day sales ban over allegedly misleading advertising of Autopilot and Full Self-Driving capabilities, a move that would devastate Tesla’s largest single market.

Simultaneously, a wrongful death trial in Miami centres on Autopilot’s role in a fatal 2019 crash, with potential punitive damages that could establish precedents for autonomous vehicle liability. Legal experts suggest the outcome could fundamentally reshape how self-driving technologies are marketed and deployed. Tesla’s very own Trolley Car Problem.

Beyond these headline cases, Tesla faces a growing constellation of “phantom braking” complaints, quality control lawsuits, and antitrust challenges to its repair monopoly. Each represents not merely financial exposure but further erosion of consumer confidence in Tesla’s core technologies.

Central to Tesla’s current predicament is a business model that once represented revolutionary thinking but now appears increasingly anachronistic. The company’s rejection of traditional franchise dealerships delivered early advantages in pricing control and customer experience, yet state-level dealership protection laws have created a patchwork of legal restrictions that limit Tesla’s expansion opportunities.

More problematically, Tesla’s insistence on controlling all aspects of vehicle servicing has created what consumer advocates term a “repair monopoly.” Owners face extended delays, higher costs, and limited alternatives when vehicles require maintenance, issues that traditional franchise networks handle through distributed infrastructure and competitive pricing.

“The direct-to-consumer model worked brilliantly when Tesla was a premium niche player with devoted customers,” observes automotive retail consultant James Morrison. “But mass-market consumers expect convenience and choice that Tesla’s current structure simply cannot deliver at scale.”

Industry data supports this assessment. Whilst traditional manufacturers leverage dealer networks to manage demand fluctuations and regional variations, Tesla must shoulder these burdens independently. The resulting bottlenecks in service capacity and inventory management become particularly acute during periods of market stress.

Reports from Tesla’s Fremont headquarters suggest Musk has resumed the hands-on approach that characterised the company’s early years, reportedly employing Musk’ peculiar trademark of sleeping at the facility whilst personally directing sales strategy. The company has rolled out aggressive incentive programmes including discounted financing, complimentary software trials, and targeted offers for military veterans and educators.

These measures represent classic demand stimulation tactics, designed to shore up quarterly numbers ahead of Tesla’s earnings announcement. However, automotive industry veterans express scepticism about their long-term effectiveness.

“Incentives are a sugar rush,” explains former General Motors executive Patricia Williams, now an independent consultant. “They can mask underlying problems temporarily, but they don’t address fundamental issues of product competitiveness or brand perception. Tesla’s challenges are structural, not tactical.”

Stock market analysts echo this assessment, noting that Tesla’s current crisis encompasses precisely the factors that discount-driven sales campaigns cannot address: ageing product lines, manufacturing inefficiencies, legal liabilities, and consumer sentiment.

Tesla’s recovery requires acknowledgement that its original advantages have largely evaporated. The company’s technological lead has narrowed considerably, with competitors matching or exceeding Tesla’s capabilities in areas from battery range to autonomous features. Meanwhile, manufacturing cost advantages have disappeared as established automakers achieve economies of scale in electric vehicle production.

Perhaps most critically, Tesla must confront the limitations of its direct-to-consumer model. Industry experts suggest hybrid approaches, incorporating elements of traditional franchise or agency partnerships, could address current bottlenecks whilst maintaining some operational control.

“Tesla needs to swallow its pride about the dealership model,” argues automotive strategist David Chen. “The best aspects of direct-to-consumer can be preserved whilst addressing the very real scalability and service issues that are alienating customers.”

Similarly, product renewal cannot wait for revolutionary technologies. Tesla requires incremental but meaningful updates to its existing range, coupled with genuinely new models that recapture market imagination.

Where is the Tesla equivalent ‘Dolphin Surf’ or WuLing Baojun’s funky “Yue Ye” a Suzuki Jimny impersonator, on price and desirability?

Tesla’s current predicament represents more than routine corporate turbulence. The company faces simultaneous challenges across every aspect of its operations, from product development to legal compliance to consumer perception. Musk’s personal intervention in sales operations, whilst symbolically significant, addresses none of these fundamental issues.

The electric vehicle market Tesla created has matured beyond recognition, populated by government funded capable competitors offering consumers genuine alternatives. Tesla’s survival depends not on charismatic leadership or promotional campaigns, but on systematic operational reform that acknowledges this new reality.

Whether Musk and his leadership team possess the humility to undertake such reform remains the critical question facing Tesla shareholders, employees, and customers. The company’s next chapter will be written not in boardrooms or Twitter feeds, but in the quotidian work of building better products and serving customers more effectively than increasingly capable rivals.

The Tesla revolution may be ending. What comes next depends entirely on the company’s willingness to evolve beyond the mythology that created it.